Payment Fees Per Transaction
Payment processing fees are the charges that move money from a customer’s payment method to a merchant’s bank account. Each card payment usually involves multiple parties: the customer’s issuing bank, card networks, a merchant’s acquiring bank, and a payment gateway or processor that routes authorization and settlement. The merchant sees a combined bill that often includes a per-transaction fee, a percentage of the amount, and separate network or compliance charges.
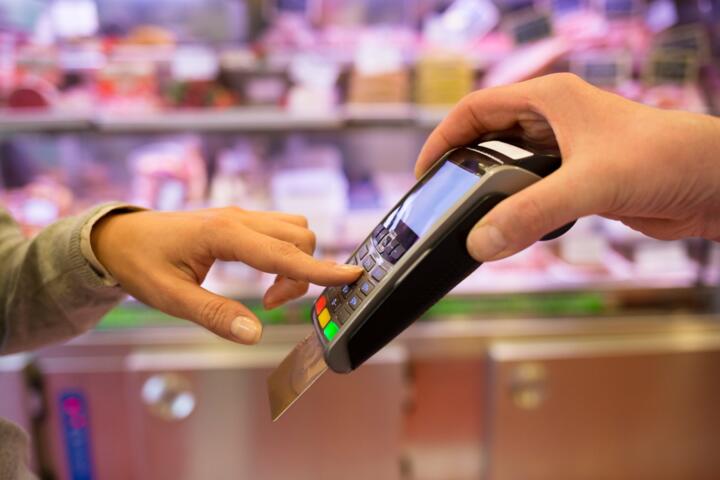
For example, a $50 card purchase at a retail store can trigger an authorization request, then later settlement. During settlement, the merchant’s bank account receives the net amount after fees. Those fees can differ by card type (debit vs credit), card brand, transaction size, and whether the payment is present (chip/tap) or keyed online. Even when the customer pays the same total price, the merchant’s cost can vary by payment method.
Readers often focus on the headline “percentage fee,” then miss the add-ons that appear as line items on statements. A processor might quote “2.9% + 30¢,” but the statement can also show network assessments, chargeback fees, monthly gateway fees, and sometimes a separate cost for cross-border processing. The net effect depends on the mix of transactions and the provider’s pricing model.
Where Costs Get Hidden
People commonly misread fee structures because they treat every transaction as identical. In practice, authorization and settlement behave differently for card-present versus card-not-present payments, and risk controls can change outcomes. A payment that gets approved quickly can still cost more if it routes through a different network or triggers additional verification steps.
Another frequent misunderstanding is assuming the processor controls all pricing. Card networks set many of the network assessments, and issuing banks influence interchange rates. The acquiring bank and processor pass through some of those costs, then add their own markup for services like routing, fraud screening, and reporting. When a provider changes routing rules, the merchant can see fee changes even if the contract’s headline rate stays the same.
Supporting technologies also affect cost. Payment gateways handle tokenization, encryption, and fraud checks; they may charge per transaction or per authorization. Fraud tools can reduce losses, but they can also increase declines or push some transactions into higher-cost categories. If you ever saw a “soft decline” that later succeeds, that pattern can still generate extra processing events behind the scenes.
Chargebacks are another hidden driver. When a customer disputes a transaction, the merchant may pay a chargeback fee and lose the transaction amount until the dispute resolves. The cost is not only the fee; it also includes time spent responding and the possibility of higher future risk fees. Some processors also apply penalties based on chargeback ratios.
How To Estimate Total Cost
Break Fees Into Components
Start by listing the fee types that appear on your merchant statement. Look for a per-transaction component (often a fixed cents amount), a percentage component, and any separate line items labeled network fees, assessments, or pass-through charges. Then add non-transaction fees such as monthly gateway access, PCI-related costs, and statement or reporting fees. If the provider quotes a “blended rate,” ask for an itemized example for at least three transaction sizes.
When you compare offers, use a consistent set of assumptions: card-present vs card-not-present mix, average ticket size, and expected approval rate. A small change in average ticket size can move the percentage portion enough to matter. I once saw a quote that looked cheaper at $100 average ticket size but became more expensive at $25 because the fixed cents fee dominated; the statement later confirmed the shift.
Model Your Payment Mix
Fees change with payment method. Debit cards often have different interchange and network assessments than credit cards, and rewards cards can carry different interchange categories. Online payments can also trigger different risk scoring and may route differently than in-store chip transactions. If you accept wallets like Apple Pay or Google Pay, the underlying transaction still uses card rails, so the cost typically reflects card interchange plus network and processor fees.
Build a simple spreadsheet with rows for each payment type and columns for count and average amount. Then apply the provider’s pricing terms to each row. If the provider offers tiered pricing, include the tier thresholds and estimate how many transactions land in each tier. A practical check: take your last month’s data and compute the fee estimate using the same date range; pricing models can change, and a “current month” snapshot can mislead.
Check Chargeback And Risk Terms
Ask for the chargeback fee schedule and how the provider calculates chargeback ratios. Some contracts charge a fee per representment attempt, and others charge only when a dispute is filed. Also check whether the processor charges for fraud screening events or for additional verification steps. If your business has recurring billing, confirm how disputes are handled for installments and whether partial refunds create extra events.
For measurable outcomes, track your dispute rate and approval rate before and after changes. A decline in approval rate can reduce revenue even if fees per approved transaction drop. If you use a gateway, note the version of your integration and the date of changes; I’ve seen merchants blame “higher fees” when the real issue was a configuration update that increased retries. In one case, a gateway setting changed around 2024-11, and the statement showed more authorizations than expected.
Validate With A Test Batch
Before switching providers, request a test environment or a sample statement analysis. Many processors can run a “pricing simulation” using anonymized transaction data. Use at least a few weeks of real transactions, including the mix of card types and channels. Then compare the simulated fees to your current statement totals.
During validation, confirm what “settlement” means in the quote. Some providers quote fees on authorization events, others on settlement events, and some include both. Also check whether tips, shipping, taxes, and refunds are treated as separate line items for fee purposes. A common frustration: the contract language may define fees by event type, while the statement groups them by day, which makes reconciliation feel like guesswork.
Educational Case Examples
Scenario 1: Small online retailer with mixed tickets. A merchant sells accessories online and averages $28 per order. Their current processor charges a blended rate with a fixed cents component. After switching to a new gateway, the merchant notices higher fees on smaller orders because the fixed cents portion increases the effective percentage. The merchant also sees that refunds generate additional transaction events, raising the total cost per completed sale. The fix was to model fees by order size buckets and to confirm refund handling terms in the contract.
Scenario 2: In-store café with card-present dominance. A café processes mostly chip-and-tap payments at the counter. Their statement shows lower per-transaction costs than their online ordering partner because card-present interchange categories differ from card-not-present categories. When they added a new online ordering flow, the processor routed those transactions as card-not-present, and the merchant’s average fees rose even though sales volume stayed steady. The café reduced the impact by improving checkout completion and reducing abandoned carts, which lowered the number of failed authorizations.
Fee Comparison Checklist
| Fee Type | Where You See It | What Drives It | How To Compare |
|---|---|---|---|
| Per-transaction fee | Statement line items; sometimes bundled | Authorization/settlement events; ticket size | Use multiple ticket sizes, not one average |
| Percentage fee | Quoted as “X%” or blended rate | Card type, channel, routing | Compare by payment mix and approval rate |
| Network assessments | Pass-through charges | Card brand and transaction category | Ask for pass-through examples from statements |
| Gateway and compliance | Monthly fees; PCI-related items | Integration method; compliance scope | Confirm monthly totals and what’s included |
| Chargebacks | Dispute fees; reversals | Dispute rate; representment rules | Request fee schedule and ratio thresholds |
Step-by-step checklist for a fee comparison:
- Export your last 30–90 days of transactions with counts by channel (card-present vs card-not-present) and average ticket size buckets.
- Collect your current statement totals for fees, refunds, and chargebacks; reconcile by date range.
- Ask each provider for an itemized pricing example using your data, including pass-through network fees.
- Verify whether the quote charges on authorization, settlement, or both; confirm how retries are billed.
- Include monthly gateway fees and any per-user or per-location fees in the comparison.
- Model a “worst month” using your highest dispute month and your lowest approval month.
- Confirm contract terms for early termination, statement access, and dispute handling timelines.
Common Mistakes To Avoid
One mistake is comparing only the headline rate while ignoring fixed fees and pass-through charges. A quote that looks cheaper at $100 average ticket size can become more expensive at $20 because the fixed cents fee dominates. Another mistake is using a single month of data that contains unusual promotions or seasonal spikes.
Merchants also miss the difference between “approved” and “attempted” transactions. Some pricing models charge per authorization event, so a checkout flow with retries or timeouts can raise costs even if revenue stays stable. If you see more authorizations than expected, check gateway logs and retry settings before signing a new agreement.
People sometimes assume refunds reverse fees automatically. In many setups, refunds reduce revenue but do not always reverse every fee component, and some systems treat refunds as separate events. If you sell subscriptions, confirm how partial refunds and billing adjustments affect fee calculations.
Another practical error is failing to read chargeback terms. Contracts can define dispute fees and representment rules differently, and some providers apply additional fees for certain reason codes. If you track disputes in a tool like Stripe Dashboard or a processor portal, export the dispute history and compare it to the contract schedule; the numbers rarely match until you map reason codes.
FAQ
What fees apply to card payments?
Card payments typically include a processor or acquiring fee plus card network assessments and interchange paid to the issuing bank. Statements may also show gateway fees, compliance-related items, and chargeback-related fees when disputes occur.
Why do online transactions cost more?
Card-not-present transactions often fall into different interchange categories and may trigger additional fraud checks or routing rules. Failed attempts can also create extra authorization events that add cost.
Do refunds reduce processing fees?
Refunds reduce the transaction amount, but fee reversal depends on the pricing model and the event type. Some fee components may not reverse fully, so total cost per sale can still rise when refund rates increase.
How can I compare two quotes fairly?
Use your own transaction data by channel and ticket size, then request itemized examples that include pass-through network fees. Confirm whether pricing applies to authorization, settlement, or both, and model chargebacks and refunds.
What should I ask about chargebacks?
Ask for the chargeback fee schedule, representment fees, and any ratio thresholds that change pricing. Also confirm dispute timelines and what evidence requirements apply for your transaction types.
Author's Insight
Payment processing fees come from multiple layers: interchange set by issuing banks, network assessments set by card brands, and processor or gateway charges for routing, reporting, and risk controls. Because the merchant statement blends these layers, the most reliable comparison uses your own transaction history rather than a single quoted rate. Contracts often define fees by event type, so authorization retries and refunds can change total cost even when sales totals stay steady. A careful approach is to reconcile statement totals by date range, then run a fee simulation using bucketed ticket sizes and your actual channel mix.
Key Takeaways
- Transaction cost usually includes both a percentage and a fixed per-event fee, plus pass-through network assessments.
- Card-present and card-not-present channels often carry different interchange categories and different risk handling.
- Refunds and chargebacks can create extra events and fees, so model them using your real history.
- Fair comparisons require itemized examples and clarity on whether pricing applies to authorization, settlement, or both.